IRS Installment Agreements: Your Clear Path to Tax Debt Resolution and Peace of Mind
An IRS installment agreement provides a structured payment solution, enabling you to repay federal taxes in manageable monthly installments while halting many aggressive collection actions. This guide explains how these agreements work, when short-term or long-term plans are suitable, required documentation, and how alternatives like an Offer in Compromise (OIC) or Currently Not Collectible (CNC) status compare. A well-structured payment plan offers crucial breathing room and a predictable route back to compliance. We’ll cover definitions, application processes, costs, risks, modification options, alternatives, and when to seek professional assistance. We utilize current terminology and forms (Form 9465, Form 433-F, Form 656, and Form 433-A/B) to empower you to choose the right federal tax payment plan.
Understanding IRS Installment Agreements: What They Are and How They Work
An IRS installment agreement transforms a lump-sum federal tax liability into manageable monthly payments, helping taxpayers avoid immediate enforcement actions like levies. This formal agreement with the IRS outlines your payment amount, frequency, and term. Direct debit can automate payments, reducing default risk. The main advantage is predictability: you maintain filing compliance while systematically repaying principal, interest, and penalties. Understanding these fundamentals is key to choosing between short-term and long-term approaches and ensuring timely payments keep collection actions at bay.
Exploring Your Options: Different Types of IRS Installment Agreements
Installment agreements are tailored to your debt size, ability to pay, and repayment timeline. Short-term plans resolve balances within 120 days with minimal paperwork. Long-term plans can extend up to 72 months, often requiring detailed financial disclosure. Direct Debit Installment Agreements (DDIAs) offer reduced user fees and lower default risk through automated withdrawals. Partial Payment Installment Agreements (PPIAs) allow lower monthly payments when full repayment isn’t immediately feasible. Your choice depends on your total debt, cash flow, and comfort with continued interest and penalties.
- Short-term plans are ideal for taxpayers who can clear their balance within a few months.
- Long-term plans suit those needing multi-year repayment and are prepared to submit financial details.
- Direct debit agreements significantly reduce the chance of missed payments and may even lower setup fees.
- Partial payment agreements apply when your assets and income genuinely justify lower monthly payments.
The next section covers eligibility requirements for each approach.
Do You Qualify? Eligibility for IRS Payment Plans
Eligibility for an IRS payment plan requires current filing compliance, an outstanding federal tax liability, and meeting specific debt thresholds. All required returns must be filed, as unfiled returns prevent approval. Debt thresholds vary: online streamlined agreements cover lower balances, while larger debts may require Form 433-F or Form 433-A/B financial disclosures. Accurate documentation of income, expenses, and assets expedites negotiations and reduces denial risk.
- File all your required federal tax returns *before* requesting a payment plan.
- Gather proof of income, bank statements, and monthly living expenses for your submission.
- Understand that larger debts frequently require detailed financial statements and thorough IRS review.
- Be aware that noncompliance or recent enforcement actions could restrict your eligibility.
Clear documentation strengthens your request and prepares you for applying online, by mail, or by phone, which we’ll cover next.
For expert professional assistance, Taxx Resolution Inc., a division of Taxx Nation Inc., specializes in resolving complex IRS tax problems. We clarify which installment agreement best fits your situation, negotiate manageable payment plans, stop aggressive collection actions, and guide you on forms like Form 9465 and Form 433-F. We invite prospective clients to a complimentary consultation to review options and outline next steps.
Your Step-by-Step Guide: How to Set Up an IRS Installment Agreement
Setting up an installment agreement requires choosing the right application channel, completing forms, and providing documentation of your ability to make consistent monthly payments. The IRS accepts online, mail, or phone applications. The process starts with calculating your owed tax, interest, and penalties, then determining a realistic monthly payment based on your finances. Thorough preparation reduces processing time and boosts approval chances. Use the checklist below before submitting your request.
- Calculate your balance: Accurately verify your assessed tax, accrued interest, and penalties directly from your IRS account.
- Choose an application channel: Decide between online, mail, or phone, considering your debt size and case complexity.
- Prepare documentation: Collect recent pay stubs, bank statements, and expense records to strongly support your proposed monthly offer.
- Select payment method: Direct debit is highly recommended to minimize missed payments and reduce default risk.
These pre-application steps lead to channel-specific instructions and required forms.
Choosing Your Application Path: How to Apply for an IRS Payment Plan Online, by Mail, or Phone
Online applications are fastest for eligible taxpayers with smaller balances, using the IRS online tool for streamlined agreements. Mail applications require Form 9465 and financial statements, sent to the IRS address on your notice; include contact info and supporting documents to avoid delays. Phone requests are for direct dealings with a revenue officer or representative, often needing follow-up paperwork. All channels involve verification, potential collection holds, and IRS confirmation of terms.
- Create or access your IRS online account for faster identity verification and convenient status checks.
- When mailing, always enclose Form 9465 and Form 433-F or 433-A/B as specifically requested by your IRS notice.
- For phone negotiations, meticulously record dates, names, and confirmation numbers, and always follow up in writing.
- Remember that opting for online direct debit can reduce setup fees and significantly lower default rates.
Understanding these channels helps you choose the most effective submission method. The next subsection explains essential forms.
Essential Forms for Your Agreement: What Documentation the IRS Requires
Form 9465 is your standard request for an installment agreement, detailing basic debtor information and proposed payment. Form 433-F or Form 433-A/B provide detailed financial disclosures to verify your ability to pay; Form 433-F is for general use, while Form 433-A/B distinguishes individual/business finances. Supporting documents like pay stubs, bank statements, and expense evidence substantiate your proposed payment and speed up resolution. Accurate completion and attachment of all necessary documentation reduce IRS back-and-forth and increase approval chances.
- Form 9465 is your initial request for the installment plan and basic contact/financial details.
- Form 433-F provides a standardized financial snapshot for ability-to-pay reviews.
- Form 433-A/B differentiates between individual versus business financial disclosures.
- Always attach recent pay stubs and bank statements to support your income and expense entries.
Accurate forms submission expedites cases. The next section examines costs, fees, and consequences of payment plans.
Understanding the Full Picture: Costs, Fees, and Consequences of IRS Payment Plans
An installment agreement includes setup fees, ongoing interest, and penalties until your tax is fully paid. Understanding these costs is vital. IRS setup fees vary by payment method (direct debit vs. non-direct debit) and application channel; direct debit agreements usually have lower fees. Interest compounds on your unpaid balance, and failure-to-pay penalties add a percentage over time. Longer terms increase total cost. Awareness of these fees helps you decide on repayment horizon or explore alternatives like OIC or CNC.
Plan Type | Typical Fee | Key Cost Driver |
|---|---|---|
Short-term Agreement | Lower or no user fee for quick payoffs | Speed of repayment significantly reduces interest accrual |
Long-term Installment Agreement | Moderate setup fee, often lower with direct debit | Extended term length increases total interest and penalties |
Direct Debit Installment Agreement (DDIA) | Lowest user fee due to automated, reliable payments | Reduced default risk and administrative costs for the IRS |
This table illustrates how payment method and term length impact costs. Next, we’ll detail interest and penalties.
Breaking Down the Numbers: Setup Fees, Penalties, and Interest Rates
- Setup fees vary by application method, with direct debit agreements generally incurring lower costs.
- Interest accrues from your original due date until full payment and compounds alongside penalties.
- Failure-to-pay penalties add monthly percentages, substantially increasing your total liability over longer terms.
- Shorter payoff timelines minimize overall interest and penalties, even if monthly payments are higher.
Understanding these cost drivers leads to the consequences of default and options for reinstatement or renegotiation.
Navigating Default: What Happens If You Miss Payments on an IRS Installment Agreement?
Defaulting on an installment agreement, by missing payments or failing to comply with filing obligations, triggers serious consequences. These include reinstatement demands, late penalties, and active collection efforts like liens, levies, or wage garnishment. The IRS may file a Notice of Federal Tax Lien or levy bank accounts/wages. Prompt remedial steps can stop or reverse actions. Reinstatement or modification requests, supported by updated financial documentation, can restore your agreement. Early professional representation increases your chance of avoiding escalated enforcement. Act promptly after a missed payment to request reinstatement and document hardship.
- Missed payments can quickly lead to lien filings and levies after administrative notices.
- Reinstatement may require catching up on missed installments or submitting updated financials.
- Prompt communication and thorough documentation significantly improve your odds of successful renegotiation.
- Professional representation is highly recommended when liens or levies are imminent or already active.
These default risks highlight the essential need for ongoing management and proactive modification strategies.
Staying in Control: How to Manage and Modify Your IRS Installment Agreement
Managing an installment agreement requires consistent payment monitoring, prompt responses to IRS notices, and proactive modification requests if finances shift. These actions reduce enforcement risk. Set up direct debit to lower default risk and ensure all tax filings remain current. If income drops or expenses rise, documented hardship submissions or modification requests can adjust payments. The IRS evaluates requests based on updated ability-to-pay evidence. Clear records and timely communication preserve negotiating leverage and reduce collection interruptions.
- Monitor your IRS account and bank activity monthly to confirm all payments post correctly.
- Keep all your tax returns current to remain in compliance and retain your plan eligibility.
- Submit modification requests with updated financial statements whenever your circumstances change.
- Utilize direct debit to minimize missed payments and avoid administrative complications.
These practices lead to steps for requesting modifications or reinstatements and minimizing wage garnishment and levy risk, explained next.
Adjusting Your Plan: How to Request a Modification or Reinstatement of Your Payment Plan
To request a modification or reinstatement, gather updated pay stubs, bank statements, and a clear explanation of changed circumstances (e.g., job loss, medical expenses). The IRS uses this to reassess your payment ability. File Form 433-F or Form 433-A/B if requested, including a cover letter with your modification reason, proposed new amount, and repayment timeline. Timely requests, ideally *before* a missed payment, yield better outcomes. Documenting hardship supports temporary adjustments or CNC status. If denied, appeal rights exist, and professional representation can guide you.
- Provide recent, comprehensive financial documentation to fully justify your requested modification.
- Propose a realistic monthly payment amount based on your documented living expenses.
- Request temporary relief or CNC status when payments become impossible due to genuine hardship.
- Consider professional help for appeals or complex reinstatement negotiations to ensure the best outcome.
Effectively presenting financial evidence is key to preventing wage garnishments and other severe collection actions, outlined next.
Safeguarding Your Assets: How to Avoid Wage Garnishments, Levies, and Liens While on a Payment Plan
Avoiding garnishments, levies, and liens depends on timely payments, current tax filings, and open communication with the IRS. Direct debit significantly reduces escalation risk. If you receive an enforcement notice, respond *immediately* with a clear plan, requesting a stay or modification while submitting documents. For imminent levies, a collection alternatives request or proof of hardship can pause enforcement. When self-advocacy is insufficient or time-sensitive, professional negotiation can halt or remove collection actions more quickly.
- Prioritize on-time payments and direct debit enrollment to prevent critical missed-payment flags.
- Respond quickly to all IRS notices with thorough documentation and a clear remediation plan.
- Request hardship consideration or a temporary CNC status when payments become truly unsustainable.
- Seek professional representation immediately when liens or levies are threatened to protect your assets.
These steps minimize collection risk and clarify when alternatives like an Offer in Compromise or Currently Not Collectible status might be better.
Beyond Installment Agreements: Exploring Other IRS Tax Debt Solutions
Installment agreements are one IRS tax relief option. Alternatives like an Offer in Compromise (OIC), Currently Not Collectible (CNC) status, and the IRS Fresh Start program offer distinct paths based on financial hardship and eligibility. An OIC can significantly reduce debt if you cannot pay the full amount. CNC status temporarily suspends collection when income/assets are insufficient for basic living expenses. The Fresh Start program expanded eligibility and modified lien procedures. Comparing these is crucial to determine the most effective route: settlement, temporary relief, or structured repayment. The table below contrasts key attributes.
Resolution Option | Primary Eligibility | Typical Outcome |
|---|---|---|
Offer in Compromise (OIC) | Demonstrated inability to pay full tax, considering income, assets, and expenses | Potential reduction of total tax liability if accepted |
Currently Not Collectible (CNC) | Proven financial hardship, evidenced by inability to afford basic living expenses | Collection actions suspended temporarily, offering breathing room |
Fresh Start Provisions | Taxpayers meeting modified thresholds for liens and installment qualifications | Easier access to installment agreements or relief from immediate liens |
This comparison highlights eligibility and outcomes, helping you understand each alternative. The subsections below unpack each option.
Offer in Compromise (OIC): Your Path to Reduced Tax Debt
An Offer in Compromise (OIC) allows taxpayers to settle federal tax debt for less than the full amount due to genuine economic hardship. The IRS calculates settlement offers based on your “reasonable collection potential” (income, assets, allowable expenses). Filing an OIC requires Form 656, comprehensive financial disclosures, and demonstrating your offered amount reflects your ability to pay. Processing takes months, and acceptance depends on documentation strength. Applicants must present clear, verifiable evidence. OICs are case-by-case, so realistic expectations and thorough preparation improve settlement odds.
- An OIC can reduce your tax debt when the IRS agrees your offer represents reasonable collection potential.
- Form 656 and detailed financial disclosure are absolutely required to submit an OIC.
- Acceptance timelines vary, demanding patience and precise documentation.
- Professional guidance often dramatically improves OIC presentation and acceptance probability.
Understanding OIC mechanics helps you decide between a compromise or preserving installment agreement options.
Currently Not Collectible (CNC) Status: Temporary Relief from Tax Collection
Currently Not Collectible (CNC) status applies when a taxpayer’s income and assets are insufficient for basic living expenses. The IRS places the account in temporary non-collectible status, pausing most enforcement. Qualification requires documented hardship (e.g., unemployment, medical expenses) and current financial statements. While CNC suspends collection, taxes and penalties still accrue. The IRS may periodically review finances to resume collections. CNC offers temporary reprieve and immediate solvency, but with ongoing accrual and future balance management.
- CNC suspends collection actions but does not eliminate your underlying tax liability.
- Qualification demands detailed financial documentation proving your inability to pay.
- The IRS reviews CNC status periodically and may reinstate collection if your circumstances improve.
- CNC is best suited for temporary relief during periods of severe financial distress.
Knowing CNC criteria helps taxpayers decide between this temporary suspension or more permanent resolutions like an OIC.
The IRS Fresh Start Program: A New Beginning for Taxpayers
The IRS Fresh Start program broadened access to installment agreements, raised eligibility thresholds for streamlined plans, and modified lien filing standards. These provisions allow taxpayers with moderate debts to access longer-term installment options with simpler qualification. It can also reduce immediate lien filings when a payment plan is active. Recent updates (as of 11/2025) influence eligibility and procedures, making it crucial to assess Fresh Start benefits. Taxpayers should weigh these provisions against long-term financial goals, as Fresh Start changes can shift the balance between paying over time and seeking permanent reductions.
- Fresh Start expanded streamlined installment eligibility and adjusted lien procedures.
- The program can reduce immediate lien filings for taxpayers entering payment plans.
- Recent updates (as of 11/2025) directly affect thresholds and administrative processes.
- Fresh Start is particularly useful when structured repayment with reduced enforcement risk is your top priority.
Comparing these alternatives illustrates when professional help delivers significant added value, explored next.
The Taxx Resolution Advantage: Why Professional Help Matters for IRS Payment Plans
Hiring a tax resolution professional improves installment agreement negotiations, reduces enforcement risk, and saves time by handling complex paperwork and IRS communications. Professionals understand which forms to submit, how to present financial disclosures, and when to recommend alternatives like OIC or CNC. They can quickly halt levies/garnishments and navigate appeals or reinstatement requests. For complicated liabilities or imminent collection, expert representation offers unparalleled experience and procedural knowledge, reducing stress and increasing the likelihood of a favorable arrangement.
- Professionals meticulously prepare and review all necessary forms and financial statements for submission.
- Experienced negotiators can often secure more favorable payment terms or effectively stop collection actions.
- Expert representation helps ensure ongoing compliance and significantly reduces the chance of costly mistakes.
- Early professional involvement is key to preventing escalated enforcement like liens or levies.
Below, we detail how Taxx Resolution Inc. assists clients and how to schedule a complimentary consultation.
Meet Our Expert: Amit Maheshwari, EA, MBA Finance
Tax Partner
Amit is an Enrolled Agent credentialed with the IRS. As an Enrolled Agent and a seasoned Entrepreneur, he brings a wealth of experience and a commitment to assisting small businesses in achieving financial peace of mind. In today’s dynamic economic environment, businesses, particularly small enterprises, often find themselves entangled in intricate tax matters that demand specialized attention.
From IRS disputes and audits to tax debt resolution, he helps alleviate the burdens that can impede the growth and success of businesses. With a keen understanding of tax laws and regulations, he strives to provide solutions specific to the client’s situation.
Your Partner in Resolution: How Taxx Resolution Inc. Helps Negotiate and Manage IRS Installment Agreements
Taxx Resolution Inc., a division of Taxx Nation Inc., specializes in resolving IRS tax problems for individuals and small businesses through skilled negotiation, dedicated representation, and meticulous preparation of filings like Form 9465 and Form 433-F. We focus on stopping aggressive collection actions, preventing liens, and maximizing client savings by evaluating all alternatives (installment agreements, OICs, CNC) based on your financial profile. We conduct initial assessments, prepare documentation, communicate with the IRS, and pursue modifications or appeals. Our client-centric approach restores compliance while minimizing financial harm. For complex cases or imminent enforcement, professional intervention streamlines resolution and protects taxpayer rights.
- Taxx Resolution Inc. expertly negotiates with the IRS to establish manageable payment plans on our clients’ behalf.
- Our firm meticulously prepares all required forms and compiles comprehensive financial documentation for submission.
- Our services include dedicated representation to halt collection actions, address liens, and seek optimal outcomes.
- A complimentary consultation is readily available to review your individual circumstances and outline clear next steps.
This leads to how to book your free consultation and what to expect during this initial engagement.
Ready for a Fresh Start? Schedule Your Free Consultation to Resolve Your IRS Tax Debt
Schedule a complimentary consultation to begin resolving your IRS tax debt. During this meeting, we’ll review your case, documents, and options. A seasoned professional will assess your filing status, balances, and paths forward (installment agreements, OIC, CNC). For efficiency, prepare recent tax returns, IRS notices, pay stubs, and bank statements. These enable an initial assessment and help us recommend next steps. The consultation covers timelines, documentation, and our representation services. Acting promptly after IRS notices significantly improves your chances of stopping collection actions. Booking your consultation initiates a structured plan tailored to your goals and financial realities.
- Bring your recent tax returns and any IRS notices to the consultation for a focused, productive review.
- Expect a clear assessment of your best-fit options: installment agreement, OIC, or CNC considerations.
- Our professional will outline the documentation needed and a recommended timeline for decisive action.
- Early consultation dramatically increases your opportunity to prevent escalated enforcement.
This concludes our guide, providing concrete options to manage your federal tax debt and pursue the most appropriate IRS payment plan.
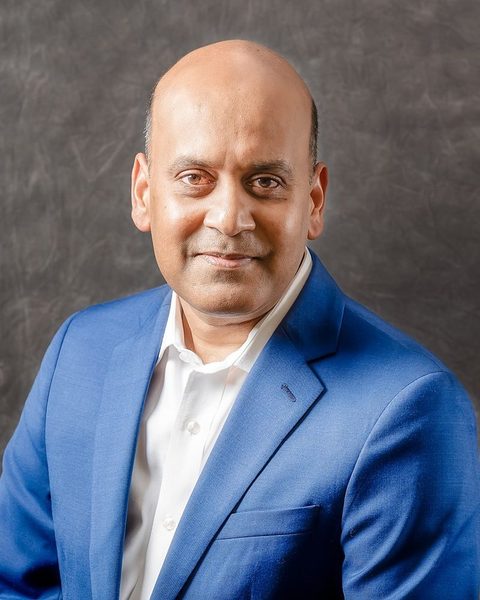
Written by
Amit Maheshwari, EA (Enrolled Agent, Licensed to Practice before the IRS)
Tax Resolution Specialist at Taxx Resolution Inc
Amit is an Enrolled Agent credentialed with the IRS. As a seasoned Entrepreneur, he brings a wealth of experience and a commitment to assisting small businesses in achieving financial peace of mind. From IRS disputes and audits to tax debt resolution, he helps alleviate the burdens that can impede the growth and success of businesses. With a keen understanding of tax laws and regulations, he strives to provide solutions specific to the client's situation.
Need Help With Your Tax Situation?
Book a no-obligation tax resolution case evaluation with a licensed tax professional.
Case Evaluation
Book a no-obligation tax resolution case evaluation with a licensed tax expert today.
(331) 215-7663